

How Grocery Spending Changes When a Household Gets Smaller
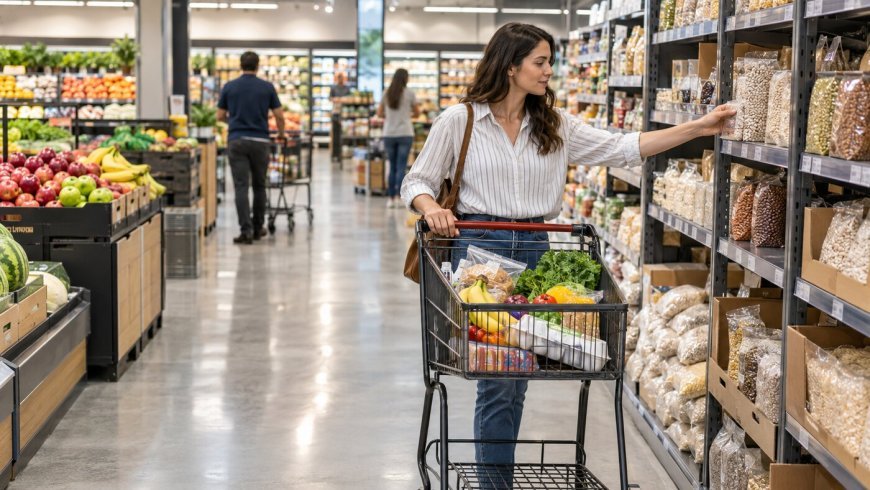
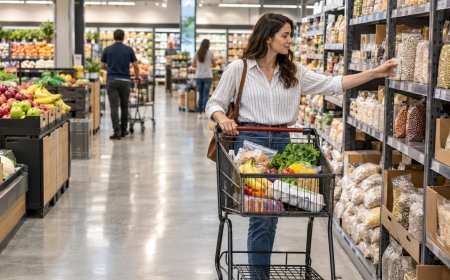
A smaller household often buys less food but may pay more per serving because bulk packages and familiar recipes no longer fit. This guide focuses on practical household choices, costs people commonly overlook and records worth keeping. It is designed to help readers make a calmer decision without assuming that one answer fits every family.
Start with the real household goal
Before acting, define what success means. It may be avoiding a fee, reducing waste, improving convenience, protecting cash flow or keeping better records. A clear goal prevents a small decision from becoming a complicated project. Use recent statements, receipts and an ordinary month as the baseline.
Package size matters
The lowest unit price fails when food spoils. The useful step is to compare the choice with actual household behavior instead of relying on a rule of thumb. Check dates, amounts and practical tradeoffs before changing anything.
Old recipes create leftovers
Scale recipes and freeze portions promptly. A quick monthly review can show whether this issue is costing money or merely creating clutter. Write down what happened, what it cost and what would prevent a repeat.
Convenience can be reasonable
Smaller prepared portions may reduce waste. Small decisions become expensive when they repeat automatically. A reminder, separate savings bucket or short checklist can turn the better option into the default.
Membership stores need a new test
Oversized perishables can erase fuel and staple savings. Price is only one part of the decision. Time, safety, convenience, taxes and the chance of needing the money soon should also be included.
Social meals change the pattern
Dining with friends can shift spending categories. Keep supporting records while they are easy to find. Receipts, screenshots, statements and confirmation emails are more useful than a year-end reconstruction.
Nutrition needs may shift
Protein, fiber and easy preparation may deserve priority. Households do not need a perfect system. They need one clear enough to use during a busy week and flexible enough to adjust when needs change.
A two-week log reveals the truth
Track what is purchased, eaten and discarded. Before committing, test the idea on a small scale when possible. A trial period reveals hidden costs and makes it easier to reverse course without a large loss.
Run the numbers without overcomplicating them
List the upfront cost, recurring cost and any fee or tax consequence that could change the answer. Estimate how often the product, service or habit will actually be used. A cheaper option that is wasted or ignored can cost more than a slightly higher-priced option that fits daily life.
When the decision involves a contract, loan, tax rule or insurance policy, read the current terms rather than relying on a headline. Rules and prices change, and an exception can matter more than general guidance.
Create a simple review point
Choose a date to check the result. Review the next statement, examine condition and use after thirty days, or confirm that a receipt and explanation are stored together. If the choice did not work, adjust it without treating the first attempt as a failure.
Questions worth asking before you decide
Ask what happens if the price rises, the household schedule changes or the product is used less than expected. Check whether cancellation, resale, repair or a lower-cost substitute is available. If another person shares the expense, agree on who will monitor it and where records will be stored.
Separate a true need from a convenience and from a wish. Protect the need first, decide what the convenience is worth and give the wish a clear spending limit. That order makes the final choice easier to explain and maintain.
Make the plan easy to maintain
Use automatic reminders, clearly labeled folders or savings buckets, and one regular review date. Avoid creating so many categories that the system becomes a second job. A five-minute check that happens monthly is more valuable than a perfect spreadsheet abandoned after a week.
Include other people affected by the decision. A partner, parent or older child may know about a schedule conflict, renewal or household priority that changes the calculation.
A practical way to put the advice into action
Begin with a short inventory. Write down what the household already owns, pays for or has saved, along with the next important date. Identify the one weak point most likely to create a fee, rushed purchase or missed opportunity. Fix that issue before adding a new product or complicated strategy.
Compare two or three realistic options using the same assumptions. Include taxes, delivery, maintenance, time and any cost of changing course. When an option depends on a deadline, place it on a shared calendar immediately. When it depends on saving, create the transfer while the decision is fresh.
Keep a small margin for uncertainty. Prices change, family needs shift and a simple task may take longer than expected. A modest cushion and a clear stopping point protect the larger budget.
The bottom line
How Grocery Spending Changes When a Household Gets Smaller is ultimately a practical decision, not a contest to find a perfect answer. Start with accurate information, protect essential expenses and choose the option that can be repeated consistently. For decisions involving taxes, legal rights, credit or investments, verify current rules and consider qualified professional guidance.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0