
Retiring to a Smaller Home: What You Could Save and What Moving May Cost
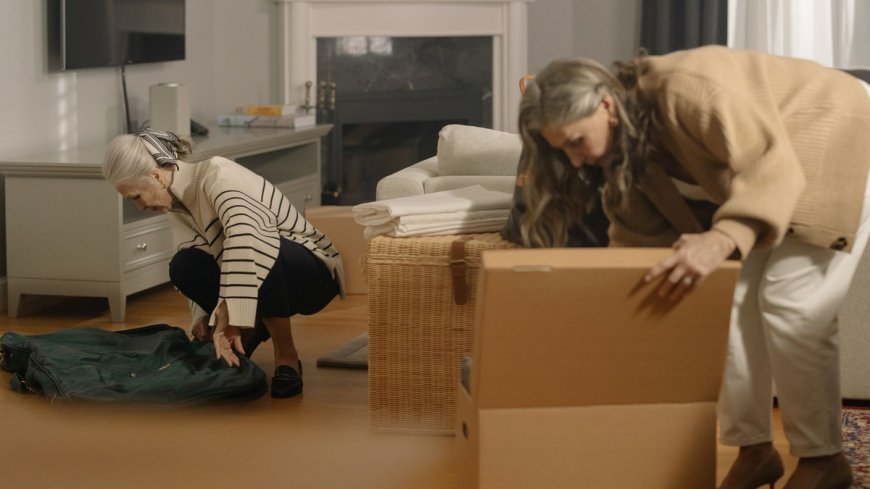
The kids moved out years ago. Two bedrooms now hold an exercise bike, a sewing machine, and boxes nobody has opened since the last move. You heat and cool every one of those rooms, mow the yard around them, and clean the gutters above them. At some point the thought shows up: would a smaller place be cheaper once we retire?
It could be. A smaller home often means lower monthly bills and less upkeep. But moving has its own price tag, and some of those costs are easy to underestimate. This guide looks at the household side of downsizing: the everyday costs that might shrink, the one-time costs of getting there, and a simple napkin test to see whether the math works for your family. It is not a guide to home loans or real estate strategy. It is about bills, stuff, and moving day.
Smaller is not automatically cheaper
Square footage is only one piece of the puzzle. A two-bedroom condo in a busy downtown could cost more each month than a larger house in a quiet town. A newer building might have lower repair bills but a hefty association fee. A home closer to family might save on travel but sit in a pricier neighborhood.
So the real question is not "big or small?" It is "what will my total monthly cost of living in this home be, and what will it cost me to get there?" Once you split the problem into those two parts, the decision gets much clearer.
It also helps to picture an ordinary Tuesday in the new place. Where will the grandkids sleep when they visit? Is there room for the hobbies you plan to pick up? Will you need to drive farther for groceries or the doctor? A home that saves $200 a month but leaves you renting a hotel room every holiday may not save much at all.
Monthly bills that could shrink
Fewer rooms usually mean less space to heat and cool. If your current utilities run about $350 a month, for example, and a smaller home brings that down to $230, that is $120 a month, or roughly $1,440 a year. Your numbers will be different, so ask the seller or landlord for a year of utility bills before you decide.
Other monthly costs may also drop. Homeowners insurance is often tied to the size and value of the home, so a smaller place could carry a lower premium. Property taxes vary widely by town, but a lower-value home may come with a smaller bill. Water, trash, and internet usually stay about the same, so do not count on savings there.
Upkeep, yard work, and cleaning
Maintenance is where many downsizers feel the biggest relief. A common rule of thumb is to set aside around 1 percent of a home's value each year for repairs and upkeep. On a $400,000 house, that is about $4,000 a year. On a $250,000 condo, the same rule suggests about $2,500. Treat these as rough planning numbers, not promises, since older homes can need far more.
A smaller yard can cut lawn service, mulch, and the steady trickle of hardware store trips. Fewer rooms mean less to clean, fewer windows to wash, and fewer light bulbs to change. If you currently pay for help with any of these chores, those savings count too. And the hours you get back may be worth as much as the dollars.
The one-time costs of selling and buying
This is where the math can surprise people. Selling a house usually involves agent commissions, which can take a noticeable slice of the sale price. You may also pay for repairs the buyer asks for, a deep clean, touch-up paint, or staging to help the house show well. On the buying side, there are closing costs, inspection fees, and title or attorney charges.
Exact amounts depend on where you live and the price of the homes involved, so get real estimates from local professionals early. Write down every one-time cost you can think of, even small ones like changing your address, new keys, or a locksmith. The list will be longer than you expect, and that is the point.
Moving day and the stuff problem
Then comes the physical move. A local move with a professional crew could run from several hundred dollars to a few thousand, depending on how much you own and how far you are going. A long-distance move often costs much more. Packing materials, tips for the crew, and a day or two of takeout meals add to the total.
The biggest cost driver is usually how much stuff you bring. Every box you move costs money, and many downsizers end up paying for a storage unit to hold things that do not fit. A unit at, say, $150 a month for two years is $3,600 for items you may never use again. Here is a simple sorting plan to keep that from happening:
- Keep: items you use every month or truly love.
- Give to family: heirlooms and pieces someone has actually asked for.
- Sell: furniture and gear in good shape that will not fit.
- Donate: everything else that still works.
Start sorting months before the move, one room at a time. It is slower but far less stressful, and it shrinks your moving bill.
New costs that can sneak in
Even a cheaper home can bring new monthly costs. Condos and many retirement communities charge association fees that cover things like exterior repairs, landscaping, or shared amenities. Those fees can rise over time, so ask how they have changed in recent years and whether any large special charges are planned.
You may also need new furniture that fits smaller rooms, window coverings for different windows, or parking fees if you move somewhere urban. A new area could have higher grocery prices or different utility rates. None of these are deal breakers. They just belong on the same sheet of paper as the savings.
One more cost hides in the timing. If you buy the new place before the old one sells, you could be paying utilities, insurance, and upkeep on two homes at once. Even a two-month overlap can add a few thousand dollars to the move. Building a cushion for that gap, or lining up the dates as closely as you can, keeps a good plan from turning stressful.
A napkin test for whether it pays off
You can run a rough break-even check in about 15 minutes. Here is how it works:
- Add up your estimated one-time costs of selling, buying, and moving.
- Estimate your monthly savings on utilities, upkeep, insurance, and yard care, minus any new fees.
- Divide the one-time total by the monthly savings to get the number of months to break even.
For example, if moving costs you $20,000 in total and you save $400 a month, it would take about 50 months, or a little over four years, to come out ahead. If you plan to stay ten years, that may look attractive. If you might move again in three years, the math gets shakier. This is a starting point for a conversation, not a final answer.
The bottom line
A smaller home could free up money every month and give you back your weekends. But the move itself is expensive, and that cost has to be earned back over time. This week, pull a year of your utility and maintenance bills, guess at your moving costs, and run the napkin test. If the numbers look promising, that is a good reason to start sorting the spare room.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0