Cash-Only Shops and Card Surcharges: When Paying With Plastic Costs Extra
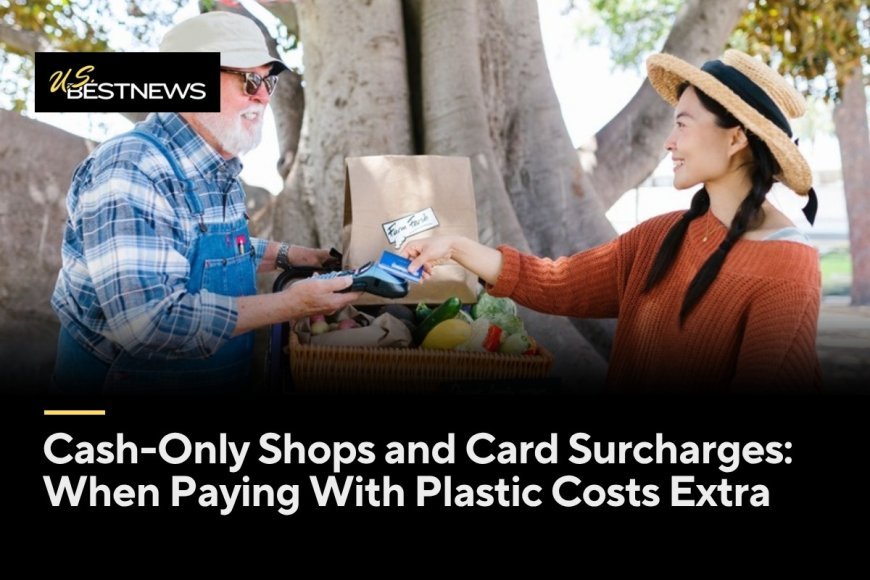
You finish lunch at your favorite cafe, hand over your credit card, and notice an extra 3% on the receipt. Or you walk into a barbershop and see a sign that says cash only. Both situations are becoming more familiar, and both raise the same question: what are businesses actually allowed to do when it comes to how you pay?
The answer is a mix of card network rules, state laws, and a few local ordinances. Plenty of shoppers carry around assumptions that are not quite right. Here are the common myths about card surcharges and cash-only shops, and what is actually true.
Myth: Credit card surcharges are illegal
Fact: In most of the United States, merchants are allowed to add a surcharge when you pay with a credit card, as long as they follow the rules. A surcharge is an extra fee meant to cover the cost the business pays to accept credit cards, often called swipe fees or processing fees.
There are exceptions. Connecticut, Maine, and Massachusetts ban credit card surcharges, and so does Puerto Rico. Colorado allows them but caps them at 2%. Other states have their own disclosure rules. New York, for example, requires businesses that surcharge to display the total price you will pay with a card, rather than tacking on a fee at the register. Because state laws can change, it is worth checking the rules where you live.
Myth: A store can charge whatever surcharge it wants
Fact: Card networks set limits. Visa's rules cap surcharges at 3% or the merchant's actual cost of accepting the card, whichever is lower. Mastercard's rules allow up to 4%, but also no more than the merchant's cost. State caps, where they exist, can be lower still.
Networks also require merchants to tell you about the surcharge before you pay. That typically means a notice at the store entrance and at the register, and the surcharge should appear as a separate line on your receipt. If you are surprised by a fee that was never disclosed, that is a red flag.
Myth: Debit cards can be surcharged too
Fact: Surcharges are not allowed on debit cards or prepaid cards under card network rules, even if you choose to run your debit card as credit and sign instead of entering a PIN. If a business charges a surcharge on your debit card purchase, it is breaking the network's rules.
This makes your debit card a simple way to avoid a surcharge without carrying cash. Just be aware that debit cards pull money straight from your checking account, and the protections are different from those on credit cards, which matters if there is a problem with the purchase.
Myth: A cash discount is the same as a surcharge
Fact: They can feel similar, but they are treated differently. A cash discount means the posted price is the card price, and you get a lower price for paying with cash. A surcharge means the posted price is the cash price, and paying by card adds a fee.
Federal law has long allowed merchants to offer discounts for paying with cash, and those discounts are generally allowed even in states that ban surcharges. You will often see this at gas stations, where pumps show separate cash and credit prices. Some businesses use cash discount programs that function almost like surcharges, so pay attention to the posted prices and the receipt.
Myth: Convenience fees and service charges are the same thing
Fact: Not quite. A convenience fee is usually a flat charge for paying in a nonstandard way, such as paying a utility bill online or by phone instead of by mail. A service charge at a restaurant is often a fee added to the bill that may or may not go to staff. Neither is the same as a credit card surcharge, and different rules can apply.
When you see an extra line on a bill, ask what it is for. Some fees are required, some are optional, and some can be avoided by choosing a different payment method.
Myth: Cash-only businesses are breaking the law
Fact: In most places, a private business can choose not to accept cards. Many small shops, food trucks, and family-run restaurants go cash only to avoid card processing fees.
The flip side is a growing number of laws that require many businesses to accept cash. These laws are meant to protect people who do not have bank accounts or cards. New York City, San Francisco, Philadelphia, New Jersey, and Massachusetts are examples of places with cash-acceptance laws, though the details and exemptions vary. In those places, many retailers cannot go fully cashless. Federal law does not require private businesses to accept cash.
Myth: Paying cash is always free
Fact: Cash has its own hidden costs. If you regularly visit cash-only shops, you may find yourself pulling money from out-of-network ATMs, which can mean a fee from the ATM owner plus a fee from your own bank. A few of those a month can cost more than an occasional card surcharge.
To keep cash costs down, use your own bank's ATMs or its partner network, or get cash back with a debit purchase at a grocery store or pharmacy, which is often free. Planning ahead for the week's cash needs can save you from last-minute ATM trips. And remember that lost cash is usually gone for good, so carry only what you expect to need.
Myth: Paying a surcharge is always a bad deal
Fact: It depends. Most rewards cards earn somewhere around 1% to 2% back on everyday purchases, so a 3% surcharge usually wipes out your rewards and then some. In pure dollar terms, paying with cash or debit is usually cheaper when a surcharge applies.
But credit cards come with protections that cash does not. If something goes wrong with a purchase, you can dispute the charge with your card issuer. If your card is stolen, federal law limits your liability for unauthorized credit card charges to $50, and many issuers offer zero liability. For a big purchase, such as a car repair or a contractor's deposit, that protection might be worth a small fee to you.
Myth: There is nothing you can do about an unfair fee
Fact: You have options. If a business charges a surcharge that seems too high, adds one to a debit card purchase, or never disclosed it, start by asking the manager about it. Many businesses will remove a fee rather than lose a customer.
If that does not work, you can contact your card issuer, which may be able to help or pass the complaint to the card network. You can also contact your state attorney general's consumer protection office, especially if you live in a state that bans or caps surcharges.
Smart habits for avoiding extra fees
A few simple habits can keep surcharges from adding up:
- Look for surcharge notices at the door or register before you order.
- Ask whether a business offers a cash price or accepts debit without a fee.
- Keep a small amount of cash on hand for places that are cash only.
- Use your debit card when a credit surcharge applies and you do not need extra purchase protection.
- Check your receipts and card statements for fees you did not expect.
Knowing the rules puts you in a better position to choose how you pay and avoid paying more than you have to.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0