


How Automatic Transfers Make Saving Easier Than Relying on Willpower
Willpower is a terrible savings plan. By Friday the month looks fine. By Tuesday night the "extra" is gone to groceries that ran hot, a birthday gift, and two "just this once" orders. Automatic transfers flip the script: money moves to savings on payday before your mood gets a vote.
This is not a complicated investing system. It is a household plumbing job. You pick an amount, pick a day, and let the bank do the boring part. When saving stops depending on remembering, it starts depending on a calendar—and calendars are more reliable than good intentions.
Why willpower loses to payday timing
Savings left in checking feels spendable. Bills, apps, and aisles are designed to help you spend it. Waiting until month-end "to see what is left" almost guarantees the answer is not much. The fix is old and still underrated: move money first, live on what remains.
Automation removes the daily debate. You are not a weaker person for needing it. You are a person who shops in a world built to interrupt thrift. A transfer that runs without you is a quiet advantage, especially in busy seasons when attention is scarce.
Start with a number small enough to survive a messy month
Pick an amount that would still feel possible after a higher electric bill or a kids' activity fee. For many households that is $25, $50, or $100 per payday—not a heroic percentage copied from a stranger online. Consistency beats a dramatic transfer that gets canceled in week three.
You can raise it later. The first win is a transfer that actually stays on. If you are rebuilding trust with yourself after failed budgets, a small automatic win is more valuable than an ambitious plan that collapses. Shame is not a funding strategy.
Time the transfer for the morning money lands
Set the automatic transfer for payday morning or the next business morning if your pay posts late. Same-day timing matters. Overnight is enough for a tempting charge to spend the raise you meant to save.
If you get paid biweekly, automate biweekly. If you get paid monthly, automate monthly. Match the rhythm so you are not guessing. Some people split: half the savings amount on each biweekly check so cash flow stays smoother between rent and groceries.
Name the destination so the money has a job
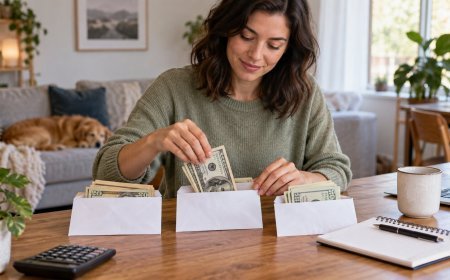
"Savings" is vague. "Emergency starter," "car repair sink," "holiday gifts," or "rent buffer" is clear. Use your bank's nickname or separate savings buckets if you have them. Named money is harder to raid for a spontaneous weekend because it feels like stealing from a future bill.
Multiple small transfers can beat one blob. Twenty dollars to emergency, twenty to car, twenty to holidays can feel painless while still building three real cushions. Just keep the total inside the amount your checking can handle after must-pay bills.
- Emergency or starter cushion
- Car and home repair sinking fund
- Holiday or birthday gift fund
- Insurance deductible or medical buffer
Use sinking funds so irregular bills stop feeling like emergencies
Sinking funds are savings with a known future job: tires, back-to-school, annual insurance, pet vet visits. Instead of scrambling when the bill arrives, you drip money toward it all year. Automation is perfect for this because the due date is predictable even when your memory is not.
Napkin example: a $600 insurance bill in six months is about $100 a month, or $50 per biweekly paycheck. Set the transfer, label it, and leave it alone. When the bill comes, you are moving money from prepared savings—not from grocery money or a credit card.
Keep a thin checking buffer so automation does not bounce
Fear of overdraft kills automatic savings. Hold a small checking cushion—often $200 to $500 depending on your bill timing—so the transfer does not collide with rent. If cash flow is tight the first month, start the auto-transfer the payday after rent clears.
Watch the first two cycles. If the transfer causes stress or fees, lower the amount rather than turning automation off. A living system at $40 beats a dead system that used to be $200. Adjust the flow; protect the pipe.
Separate "save" from "invest" for this habit
This is everyday saving, not portfolio construction. Your automatic transfer can land in a plain savings account you can reach for real life surprises. If you already invest elsewhere, fine—keep this job simple: make cash reserves happen without a pep talk every Friday.
Reachable savings reduce the chance that a flat tire becomes a credit-card story. That alone is a win worth protecting. Fancy returns can wait until the boring cushion exists and you are not living transfer-to-transfer.
Build a raise and windfall rule into the same system
When income bumps—a raise, overtime, a tax refund—increase the automatic transfer before lifestyle upgrades claim the cash. Even half the raise toward existing named goals keeps progress visible. Windfalls can send a one-time extra transfer the same week the money posts.
Write the rule once: "Payday increase? Savings transfer increases first." Future-you will not feel like negotiating every time. The system absorbs good news on purpose instead of letting it vanish into slightly nicer defaults.
Handle "I need that money back" without wrecking the habit
Real emergencies happen. That is why the account exists. If you must pull from savings, take only what the emergency needs, note why, and set a temporary boost to refill. Do not permanently delete the automation because one month was hard.
For non-emergencies—concert tickets, a mood upgrade, a sale that "won't last"—practice leaving the named funds alone. Borrowing from holiday savings in July is how December gets loud. If the want is strong, pause and fund it from the next flexible spending week instead of raiding the system.
Review quarterly, not nightly
Do not check the savings balance every evening like a scoreboard that needs dopamine. Check monthly to confirm transfers ran, and quarterly to adjust amounts for new bills or goals. Nightly staring often leads to dipping for non-emergencies.
A quarterly review checklist keeps you honest without obsession: Did every transfer clear? Did any sink fund reach its target? Should one category get a pause while another gets a boost? Adjust with a calm calendar, not a panicked scroll at midnight.
- Confirm transfers posted for the last 90 days
- Move a completed sink fund to the next goal
- Raise or lower amounts based on real cash flow
- Keep the checking cushion intact
Pair automation with one spending guardrail
Automation shines brighter with a simple guardrail: a weekly spending cap for flexible categories, or a 24-hour wait on non-grocery online carts. You do not need a perfect budget spreadsheet. You need fewer leaks while the transfer does its job.
If a transfer ever feels impossible, cut a recurring leak first—unused subscriptions, premium app tiers, duplicate streaming—then keep the savings automation alive. Protect the pipe. Adjust the flow. The goal is a setup you can leave alone most weeks.
A thirty-day setup you can finish in one sitting
Open your bank app. Create or rename a savings bucket. Choose a starter amount. Schedule the transfer for next payday morning. Write the goal name where you will see it. That is enough for day one. Over the next month, only watch whether it cleared and whether checking still breathed.
After thirty days, decide whether to bump the amount by a small step—say $10 or $25—not a dramatic leap. Stacking quiet increases beats restarting from zero after an all-or-nothing month. Boredom is a feature here. Boring transfers build balances.
Your one move on the next payday
Schedule one automatic transfer for an amount you can survive. Name the destination after a real goal. Set it for payday morning. Leave it alone for thirty days. Willpower can still choose the Friday treat. Automation makes sure saving already happened before the treat conversation starts.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0