



The $25-a-Week Habit That Can Help You Start Building Wealth
Twenty-five dollars a week rarely feels life-changing. That is exactly why it can be useful. A modest amount is easier to repeat than an ambitious savings target that disappears after one difficult month. Over a full year, the habit directs about $1,300 toward a goal before any interest or investment return.
The value is not a promise of quick wealth. It is the system: money moves before it can be casually spent, the balance becomes visible, and increasing the amount later feels like an adjustment rather than a fresh start.
Start with the right destination
If a surprise repair would force you onto a high-cost credit card, an emergency fund may be the best first destination. If you carry expensive revolving debt, extra principal payments can reduce future interest. Once those foundations are stable, a retirement account or diversified long-term investment may fit.
Do not invest money you are likely to need soon. Savings provides stability and access; investments are intended for longer timelines and can fall in value.
Make the transfer automatic
Choose a day just after payday and schedule a recurring $25 transfer. If weekly timing is awkward, use $50 every two weeks or roughly $108 per month. Keep enough checking-account cushion to prevent overdrafts. Automation should reduce stress, not create fees.
Give the money a visible job
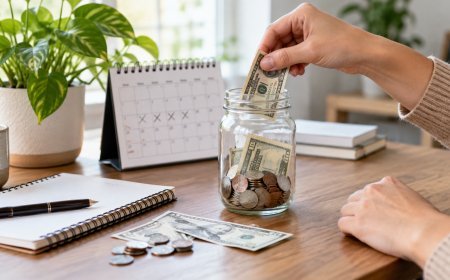
A separate savings account, labeled savings bucket, or eligible retirement account can protect the money from ordinary spending. A name such as “car repair reserve” or “future investing” is more motivating than an unexplained balance. The destination should be simple enough that you understand how to access it and what costs or restrictions apply.
Use milestones that feel real
The first $100 proves that four weekly decisions can create a result. The first $500 can soften a smaller emergency. Reaching $1,000 may reduce the chance that an unexpected bill becomes new debt. After a year, you have both a balance and twelve months of evidence that the system works.
Milestones are not universal financial rules. They are checkpoints that help you notice progress before the final goal is reached.
Find the money without pretending it is painless
Review repeated spending rather than cutting one meaningful pleasure. An unused subscription, one planned leftovers night, fewer convenience-store stops, or a negotiated recurring service may cover part of the amount. If $25 would make essentials harder to afford, start with $5 or $10. A smaller transfer that survives is better than a larger one that is constantly reversed.
Increase it when income rises
When you receive a raise, finish a payment, or reduce a bill, direct part of the difference to the transfer before lifestyle spending absorbs it. Moving from $25 to $30 is a meaningful increase but may feel manageable. Review the amount every three months and adjust only when the rest of the budget can support it.
Do not chase exciting returns
Consistency does not require a dramatic investment. For long-term investing, understand fees, diversification, risk, and account rules before choosing anything. Avoid social-media hype, guaranteed-return language, pressure to act immediately, and products you cannot explain in plain English.
The habit controls what you can control: contribution rate, regularity, costs, and time. Market performance is never guaranteed.
Create an emergency pause rule
Consistency does not mean ignoring real life. Decide when a pause is reasonable—job loss, an urgent expense, or a serious cash-flow disruption—and when it is merely tempting. Resume with the next pay period you can afford instead of treating one pause as permanent failure.
Track the habit without checking every day
A monthly review is usually enough. Confirm that transfers completed, note the balance, and make sure the goal is still appropriate. Daily checking can make long-term progress feel slower than it is. Measure months of consistency, not excitement from one week.
A practical 90-day start
In week one, choose the goal and automate the transfer. At the end of month one, confirm the schedule causes no cash-flow problems. At day sixty, remove one recurring expense that no longer earns its place. At day ninety, decide whether to keep $25, increase it slightly, or redirect the balance toward a more urgent priority.
The bottom line
Twenty-five dollars a week will not produce instant wealth, but it can build the behavior from which wealth grows: spending less than every dollar received, protecting progress from impulse purchases, and regularly funding future goals. Begin with an amount your budget can repeat, give it a clear job, and let consistency do the heavy lifting.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0